A lot of the buyers I help are surprised when they realize there are more mortgage options than they first assumed, including an adjustable-rate mortgage. One family figured a traditional fixed-rate loan was their only way to go, until we sat down and reviewed financing options that actually matched their short-term plans, a bit better.
An adjustable-rate mortgage is a home loan where the interest rate begins with a fixed rate for an initial stretch, then it changes over time based on market conditions. This sort of plan can be a solid fit for buyers who don’t expect to hold onto the home long term. If you understand how these loans work, you can probably make a better, more informed decision. So, let’s talk about the situations where an adjustable-rate mortgage might make sense, and what you should know before you choose one.
Is an Adjustable-Rate Mortgage a Good Option for Homebuyers?
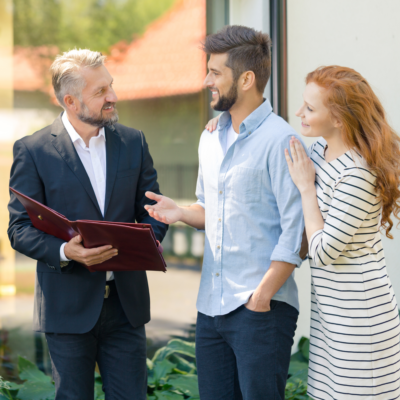
It depends. An adjustable-rate mortgage can be a smart choice if you expect to move, refinance, or pay off the loan before the initial fixed-rate period ends. After that period, the interest rate can change, so it’s important to understand how future payments may be affected.
Not long ago, I worked with some buyers who had spotted a home they really liked in Mountain View. Like a lot of people, they figured a 30-year fixed-rate mortgage was basically their only real, practical choice.Their biggest concern was keeping their monthly payment manageable without pushing their budget too far. without pushing their budget too far
The goal wasn’t to convince them to choose one loan over another. It was to help them understand how each option aligned with their financial plans so they could make a confident decision.
How Does an Adjustable-Rate Mortgage Work?
An adjustable-rate mortgage begins with a fixed interest rate for a set period, such as 5, 7, or 10 years. After that, the rate adjusts periodically based on market conditions and the terms of your loan, which can increase or decrease your monthly payment.
For buyers who might not stay in their home for the long haul, an ARM can end up looking pretty attractive because the introductory interest rate is often lower. The Consumer Financial Protection Bureau points out that most ARMs come with initial, subsequent, and lifetime rate caps too, so they don’t let the interest rate swing as much over time. When I’m talking with clients about financing options, I always try to get them to look past just todays monthly payment. We usually slow down and talk about what comes next, things like future plans, career shifts, adding to the family, and how long they honestly think they’ll hold onto the home.
In my experience Pro Tip: Before you choose any mortgage, ask yourself this one simple question: how long do I realistically expect to own this home? Your answer can help reduce the options so the loan choices worth a closer look are easier to spot those conversations clear things up more than just lining up interest rates,
Pro Tip: Before choosing any mortgage, ask yourself one simple question: How long do I realistically expect to own this home? Your answer can help narrow down which loan options deserve a closer look.
When Should You Consider an Adjustable-Rate Mortgage?
An adjustable-rate mortgage may be worth considering if you plan to own the home for only a few years or expect your financial situation to change. Reviewing your long-term plans can help determine whether this loan fits your goals.
Every buyer’s situation is different. One person buying their forever home might really like the steadiness of a fixed-rate mortgage. Another buyer thinking about moving again in five or seven years could decide that an adjustable-rate mortgage makes more sense for their objectives. In fact, adjustable-rate mortgages account for under 10% of U.S. mortgage originations, so it’s a reminder that while ARMs can work well, they’re made for specific financial situations, not basically for everyone.
That’s why I believe the best mortgage isn’t just the one with the smallest starting rate, but the one that matches your budget plans and future aims. Before you decide anything, take a look at the loan terms, figure out how the rate adjustments work in real life, and ask plenty of questions, so you can go forward with confidence.
Choosing the Mortgage That Fits Your Future
The buyers I worked with didn’t pick an adjustable-rate mortgage just because it sounded cheaper at first. They went with the option that best matched what they expected to do next, and where they thought they would be in a few years. The right mortgage really depends on your goals, your timeline, and how comfortable you feel with the possibilities, and when you understand your options you can move forward with more confidence
If you’re looking at your financing paths or getting ready to buy a home in the Silicon Valley, I’m Wendy Marioni, and I’d be glad to help you sort through it. My goal is to offer guidance that fits your exact situation, so your home-buying journey becomes The Most Supported Move You’ll Make.